
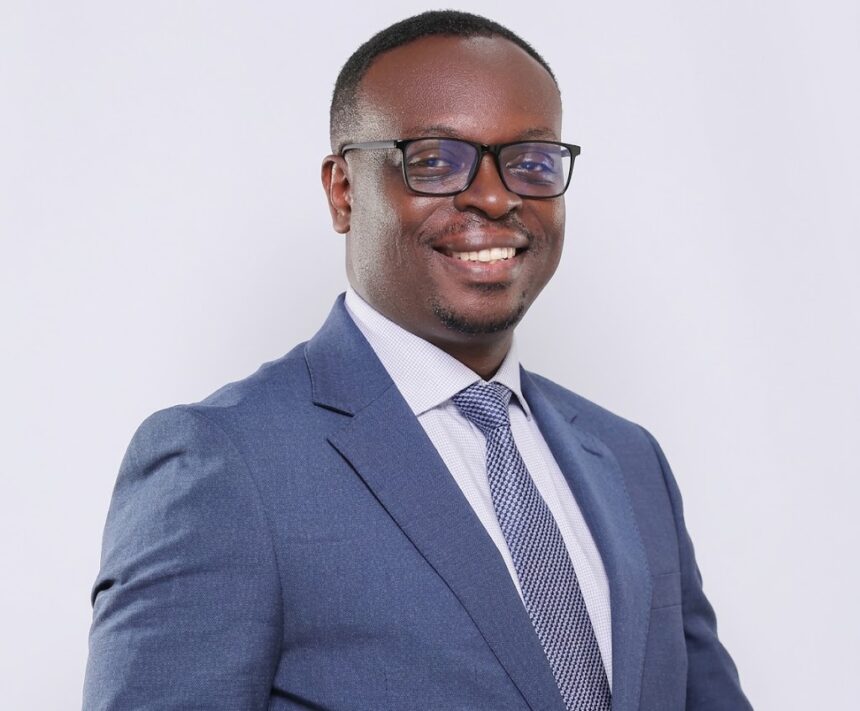
For Pearl Bank Managing Director Julius Kakeeto, scaling Uganda’s financial sector requires a simple fundamental resource: adequate fuel.
Operating in a market where indigenous banks often struggle to match foreign rivals, Kakeeto has positioned capital retention at the centre of the lender’s aggressive expansion.
Sourcing growth internally through retained earnings alongside ongoing shareholder backing, the bank’s total loan portfolio has crossed the 1 trillion Ugandan shilling ($270 million) threshold, driven by a 30% expansion in lending since late 2025.
“Capital is like fuel. It keeps you on the road,” Kakeeto emphasised, reflecting on the institution’s trajectory a year after shedding its legacy Post Bank Uganda identity.
For Kakeeto, the corporate rebrand was never merely an aesthetic update, but a foundational requirement to compete effectively, capture corporate market share, and deliver measurable economic returns within Uganda’s productive sectors.
Kakeeto’s core strategic mandate centres on marrying strict commercial discipline with a development-focused mission. Rather than dispersing capital indiscriminately, he is directing the bank’s balance sheet toward high-multiplier areas of the economy.
Agriculture currently accounts for approximately 35% of the portfolio, with Kakeeto steering exposure beyond primary cultivation toward industrial-strength, value-addition processing, and export infrastructure.
This approach directly matches the state’s broader macroeconomic priorities spanning agriculture, tourism, mineral development, and science and technology.
At the same time, Kakeeto is overseeing a radical structural migration in how the bank interacts with its customer base. Transaction flow through traditional branch networks has plummeted from 80% five years ago to just 8% today, despite overall volume surging fivefold.
By leveraging Wendi, the bank’s mobile financial platform that has routed over 3 trillion shillings in Parish Development Model funds to three million households and expanding the agency footprint toward 20,000 operators, Kakeeto aims to anchor an indigenous institution at the absolute centre of national prosperity.
“We would like to see an indigenous or home-grown bank with a local identity that is at the forefront of fostering prosperity for Ugandans in real terms with measurable and quantifiable goals that deliver impact to Uganda’s economy,” Kakeeto said.
Over the next five years, his playbook relies on combining digital delivery with affordable credit to prove that a locally owned bank can drive systemic development while maintaining market competitiveness.