
Pearl Bank has crossed the UGX 1 trillion mark in loans and advances, accelerating lending at a pace that could significantly alter the state-owned bank’s position in Uganda’s increasingly competitive credit market.
The milestone marks a sharp change from the bank’s performance in 2025, when its loan book increased by just 4.2% to UGX 749 billion. By June 2026, the portfolio had reached UGX 1 trillion, adding about UGX 251 billion in six months, according to recent reporting.
That represents growth of roughly 33.5% in half a year, compared with an annual compound growth rate of about 13% between 2021 and 2025.
The acceleration is being driven largely by agriculture and afro-industrialisation, which account for about 35% of Pearl Bank’s loan portfolio. Almost half of lending is directed towards sectors aligned with Uganda’s priorities under the Fourth National Development Plan and the government’s Tenfold Growth Strategy.
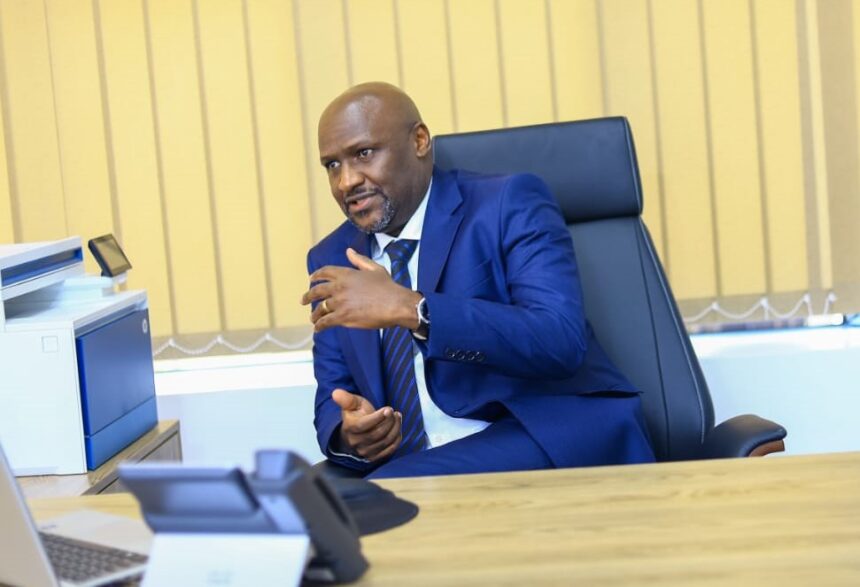
“We set ourselves the ambition of doubling our market share and then developed products that could help us scale quickly,” said Martin Mugisha, Pearl Bank’s Executive Director–Operations.
“Agriculture and agro-industrialisation have been particularly important, supported by disciplined execution across the Bank.”
Pearl Bank, formerly PostBank Uganda, has expanded lending across agricultural production, processing and related value chains, while increasing financing for MSMEs, trade, logistics and construction.
The acceleration comes against a backdrop of significantly stronger funding mobilisation. Pearl Bank’s audited 2025 results show customer deposits increased by UGX 426 billion, or 43%, to UGX 1.417 trillion, while total assets rose to UGX 1.875 trillion. Profit after tax increased 34% to UGX 47.3 billion.
The divergence between deposits and lending was notable in 2025. While deposits surged, the bank increased its loan book by only UGX 30 billion, directing a substantial portion of its balance sheet into government securities.
Recent analysis found that the bank’s loan-to-deposit ratio fell to 52.8% at the end of 2025, highlighting the funding capacity that was available before the latest lending expansion.
The rapid growth in 2026 therefore suggests that Pearl Bank is beginning to deploy more of that balance-sheet capacity into private-sector credit.
Development-finance partnerships have also become central to the strategy. Pearl Bank works with the Government of Uganda, Bank of Uganda’s Agricultural Credit Facility, Aceli Africa, aBi Finance and the Agence Française de Développement, among others, to reduce funding costs or share lending risks.
“The biggest constraint to private-sector credit remains the cost of borrowing,” Mugisha said. “Partnerships allow us either to reduce the cost of funds or share some of the lending risk.”
The challenge for the bank now is whether it can sustain the pace without compromising asset quality, liquidity or the cost of credit.
Agriculture, tourism, minerals and large construction projects can require financing over several years, creating a mismatch when banks depend heavily on shorter-term deposits to fund longer-term assets.
Pearl Bank says access to long-term capital will therefore be critical to its next phase of expansion.
“We are still on the journey towards doubling our market share,” Mugisha said. “The next phase will require stronger local and international partnerships and, critically, more long-term capital.”
The bank intends to increase lending to tourism, construction, minerals and other long-term investments under the government’s ATMS agenda — afro-industrialisation, tourism, minerals and science and technology.
Pearl Bank is also relying on digital platforms and agency banking to extend its reach without having to match loan growth with a corresponding expansion of physical branches.
The strategy comes as Pearl Bank attempts to translate the balance-sheet growth achieved since its rebranding from PostBank Uganda into a larger commercial footprint.
Its audited figures show loans and advances have risen from UGX 455 billion in 2021 to UGX 749 billion in 2025, before the latest surge pushed the portfolio beyond the UGX 1 trillion threshold.
For Pearl Bank, the significance of the UGX 1 trillion mark is therefore less about the round number than the speed at which it was reached.
The next test will be whether the bank can convert that lending momentum into sustained market-share gains while maintaining profitability, funding stability and credit quality.
That will determine whether the latest surge represents a temporary acceleration or the beginning of a more fundamental shift in Pearl Bank’s role in Uganda’s banking industry.