
By Highflyer Report
Technology is giving Ugandan banks a clearer view of agricultural businesses, potentially opening the door to more financing for farmers—but lenders say access to affordable, long-term capital remains a major obstacle to commercialising the sector.
Mercy Iselu, Sector Head for Food and Agriculture at dfcu Bank, said digital transaction records and other data sources are enabling financial institutions to assess farmers beyond traditional credit histories by providing greater visibility into production cycles, cash flows and business performance.
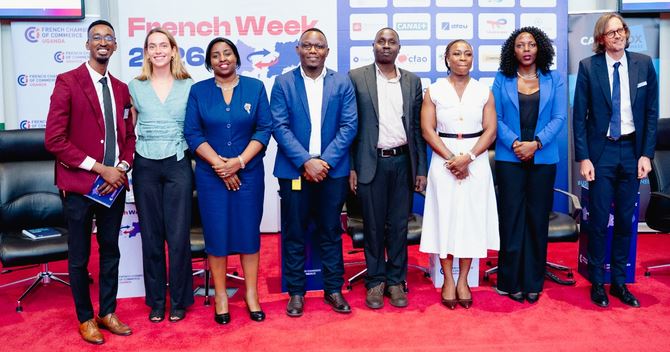
“If the bank is satisfied with the data available, it creates trust by providing verifiable evidence of a farmer’s income,” Iselu said at the French Week Business Forum at the Uganda Business Facilitation Centre.
The shift toward data-driven lending comes as Uganda seeks to move more households from subsistence agriculture into commercially oriented production. The 2024 National Population and Housing Census shows that 33.1% of households remain in the subsistence economy, compared with 66.9% operating in the money economy.
For lenders, better-quality data can provide evidence of income patterns and repayment capacity, allowing credit to be structured around the actual cash flows of agricultural enterprises rather than relying mainly on historical records or conventional collateral.
But Iselu warned that technology alone will not close Uganda’s agricultural financing gap.
Much of the available agricultural credit remains tied to seasonal production cycles, while commercialisation increasingly requires financing for machinery, irrigation, solar-powered equipment, storage and other productive infrastructure.
“Most of the financing available is based on the season. But if financial institutions want to transform the sector, there is a need for long-term financing,” she said.
That creates an opportunity for closer collaboration between banks, equipment suppliers, technology companies, insurers and other players across agricultural value chains.
Digital tools can help farmers identify crop diseases, production constraints and operational inefficiencies, Iselu said, but their economic value is limited if farmers cannot afford to implement the solutions.
“The biggest disconnect is therefore affordability and access to finance,” she said.
Dr. Sam Mugume, Acting Commissioner for Macroeconomic Policy at the Ministry of Finance, Planning and Economic Development, said agriculture remains critical to Uganda’s economic transformation because of its role in employment, production and household incomes.
He called for greater focus on productivity, with public investment in rural roads, irrigation and other infrastructure helping reduce the risks faced by agricultural lenders.
Mugume also advocated financing entire value chains rather than individual farmers, linking producers with processors, equipment suppliers, insurers, transporters and markets.
He said public financing should focus on creating conditions that can attract private investment into areas such as mechanisation and irrigation, while stronger public-private partnerships tackle structural constraints.
Therefore in view of Uganda’s agricultural sector, the emerging financing model is therefore moving beyond simply deciding whether a farmer qualifies for a loan.
The bigger question is whether banks, government and private-sector partners can combine reliable data, affordable long-term capital and infrastructure to turn fragmented farming activity into investable businesses.